
How Much of a $50,000 Injury Settlement Will I Actually Keep?
Injury Settlement: It is one of the first questions people ask when an offer arrives: if the insurer pays $50,000, how much of that is actually mine? The honest answer depends on three deductions, and the last one, medical bills and liens, is usually where the most money can be saved.
| The Short Answer |
|---|
| There is no fixed amount: from a $50,000 Georgia injury settlement, you keep what remains after attorney’s fees, case expenses, and any medical bills or liens are paid. In the hypothetical example below, that comes to about $23,000, but negotiating bills and liens can raise your share, and Georgia law limits when some health insurers can be repaid at all. Compensation for physical injuries is generally not taxable income. |
Where the Money Goes: A Hypothetical $50,000 Settlement
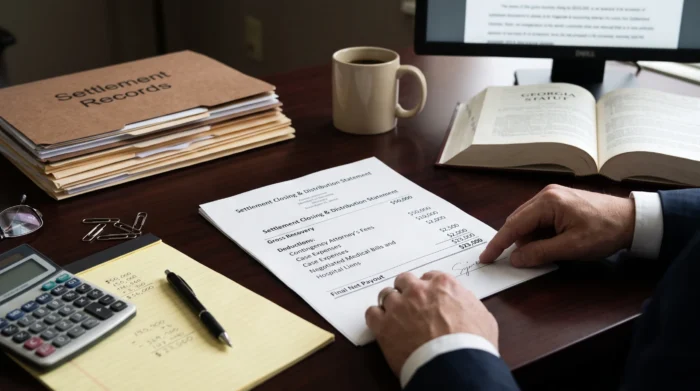
Assume a car-crash settlement of $50,000, a one-third contingency fee, $1,000 in case expenses, and $14,000 in medical bills that are negotiated down to $9,000:
| Line item | Amount |
|---|---|
| Gross settlement | $50,000 |
| Attorney’s fee (one-third, hypothetical) | − $16,667 |
| Case expenses (records, filing, and similar costs) | − $1,000 |
| Medical bills and liens (negotiated from $14,000) | − $9,000 |
| Net to you | $23,333 |
Every number in that table can change. Your fee is whatever your written agreement says. Expenses depend on how much work the case required. And the medical line moves the most: the $5,000 negotiated off the bills in this example went straight into the client’s pocket.
Attorney’s Fees and Case Expenses
Most injury lawyers work on a contingency fee, meaning the fee is a percentage of the recovery and nothing is owed if there is no recovery. Georgia’s Rules of Professional Conduct (Rule 1.5(c)) require a contingency agreement to be in writing and to explain how the fee is calculated, including whether expenses are deducted before or after the percentage is applied. In the example above, calculating the fee after expenses would leave the client about $330 more. Ask whether the percentage changes if a lawsuit is filed. At the end of the case, you are entitled to a written closing statement showing every deduction.
Medical Bills and Liens: The Biggest Variable
Who gets repaid, and how much, depends on who paid for your care:
- Hospitals and providers with liens. Georgia lets hospitals, nursing homes, physician practices, and burn-care providers claim a lien against your injury claim (OCGA § 44-14-470). To be valid, the lien must be properly perfected; a hospital must file its statement within 75 days after discharge, after giving notice (OCGA § 44-14-471). Liens that were not perfected can sometimes be challenged, and valid ones can often be negotiated.
- Health insurance. For plans governed by Georgia law, OCGA § 33-24-56.1 says the insurer can be reimbursed only if your recovery fully compensates you for all of your losses, and its claim must be reduced by its share of attorney’s fees and expenses. Self-funded employer plans and federal programs follow different rules, so the plan type matters.
- Medicare and Medicaid. Medicare must be repaid for related care it covered, although its recovery is reduced by a share of the fees and costs of obtaining the settlement (42 C.F.R. § 411.37). Georgia Medicaid also has a statutory right to recover (OCGA § 49-4-149).
- Unpaid providers. Doctors who treated you without payment, sometimes under a letter of protection, are usually paid from the settlement. Those balances are often negotiable too.
Two other items affect what you keep. A pre-settlement loan is repaid from the settlement, often with steep charges, so read the contract carefully before borrowing against your case. On the other side of the ledger, damage to your car is usually resolved as a separate property claim and does not come out of the injury settlement.
Our Settlement Liens FAQs answer more specific lien questions.
Is Any of It Taxed?
Generally, no. Under federal tax law (26 U.S.C. § 104(a)(2)), compensation for personal physical injuries is excluded from income, including the part that replaces lost wages. Punitive damages and interest are different and are usually taxable. Because individual situations vary, confirm the details with a tax professional; our Settlement Tax FAQs cover common questions.
Why So Many Offers Land Near $50,000
In Georgia car-crash cases, the settlement amount is often set by insurance limits rather than by the injury. Georgia drivers must carry at least $25,000 in bodily injury liability coverage per person (OCGA § 33-34-4; OCGA § 33-7-11), and many carry only that minimum. A $50,000 settlement is often the at-fault driver’s $25,000 policy plus $25,000 from the injured person’s own uninsured/underinsured motorist coverage (OCGA § 33-7-11). See Personal Injury Insurance and our UM/UIM Coverage FAQs for how those layers work, and our Motor Vehicle Accident practice page for how we handle these cases.
Fault, Deadlines, and What Your Claim Is Worth
Before any of the deductions above, the gross number depends on proof. Fault is shown with the police report, photos, video, witness statements, vehicle data, and medical records linking the crash to the injury. Under OCGA § 51-12-33, your recovery is reduced by your own percentage of fault and barred if you are 50 percent or more responsible, so a 20 percent fault argument can cut a $50,000 claim to $40,000 before fees are calculated.
Most Georgia injury lawsuits must be filed within two years (OCGA § 9-3-33). Claims against a city require written ante litem notice within six months (OCGA § 36-33-5), and claims involving your own uninsured motorist coverage have their own procedural requirements.
What the claim is worth turns on the injury, the medical treatment, lost income, and the effect on your life, and then on how much insurance is available. As of publication, Georgia’s 2025 tort reform law lets juries consider what was actually paid for medical care rather than only what was billed (OCGA § 51-12-1.1). Our attorneys believe parts of that law will ultimately be ruled unconstitutional under the Georgia Constitution’s guarantee of the right to trial by jury.
What Others Say About Our Work
I hold an AV Preeminent® rating from Martindale-Hubbell and have been selected to Super Lawyers® each year since 2024, after Rising Star recognition from 2017 through 2023. Other Georgia law firms refer cases to Haug Barron Law Group for litigation when those cases cannot be resolved before suit, and my law partner, Colin A. Barron, and I obtained a $30 million wrongful death verdict in DeKalb County State Court. Every case is different, and no prior result predicts the outcome of another.
“They done a great job on my case i was very pleased with the outcome”
— Cedric E., Google review, June 2026
Before You Accept an Offer — Free Consultation
Before you sign a release, ask for a written estimate of your net: the fee, the expenses, and every bill and lien, with what each one can likely be negotiated to. Once you sign, the case is over.
Before you accept any injury settlement offer in Georgia, a plaintiff-only firm that challenges improper liens, negotiates medical bills, and identifies every available source of coverage can significantly increase the amount you actually keep. Contact Haug Barron Law Group today for a free, confidential consultation to protect your right to full compensation.
This article provides general information about Georgia law and is not legal or tax advice. It does not create an attorney-client relationship. The settlement example is hypothetical. Past results do not guarantee future outcomes. Advertising does not indicate a guarantee of results. © Haug Barron Law Group, Personal Injury Lawyers. All rights reserved.
Contact Haug Barron Law Group Today for a FREE Consultation.